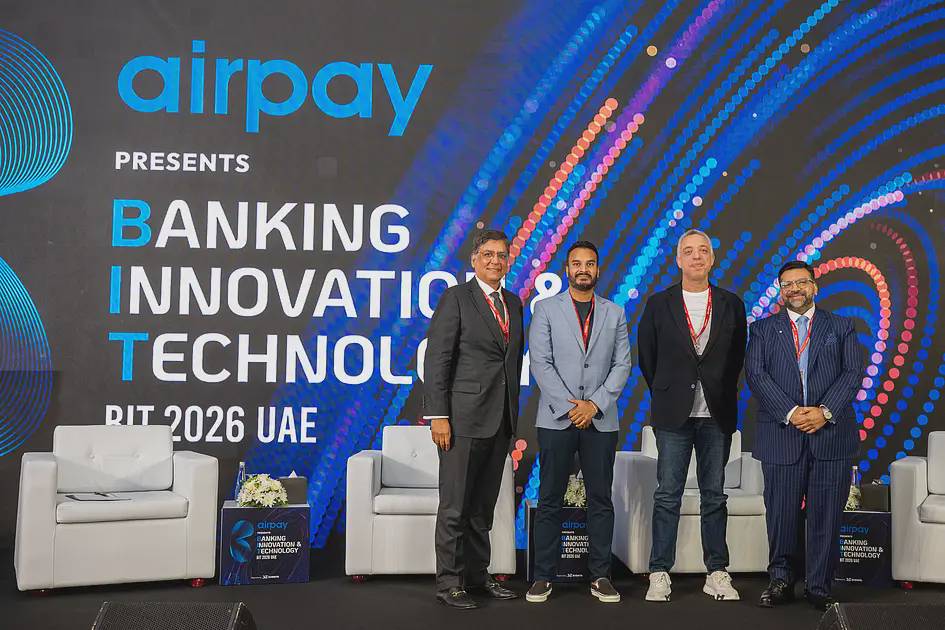
Senior UAE banking and fintech executives said at the Banking Innovation & Technology (BIT) Summit in Dubai that the industry is shifting away from traditional credit scores toward real financial-behaviour data to make faster, more accurate lending decisions.
Omair Ansari, CEO and co-founder of fintech firm ABHI, said his company draws on remittance data and Wage Protection System (WPS) records to assess customers who lack a formal credit score. He noted that 99.9 per cent of ABHI's customers have no official credit history at all, even though they have steady income and traceable financial patterns.
Walid Hassouna, founder and group CEO of Valu, described the shift as moving from "backward-looking" to "forward-looking" assessment, combining multiple layers of data to build a more realistic picture of a customer's ability to repay.
Amit Malhotra, global head of retail banking at Abu Dhabi Islamic Bank, said the future of lending will be "real-time, predictive, absolutely data-driven and customer-focused." Meanwhile, Basel Nezam of Network International and Deepak Sarup of Thriwe stressed that personal data use must come with full transparency and explicit customer consent, rather than personalisation for its own sake.
The shift carries particular weight for the UAE's large expatriate and worker population, many of whom are locked out of loans and credit facilities simply because they have short residency histories or no formal banking record. A data-driven approach could close that gap by assessing their real financial standing instead of relying on a score they were never able to build.